Quick Answer: Liability coverage helps protect construction businesses from losing money. It keeps you safe if someone gets hurt at work, someone’s property gets damaged, or an accident happens. If there is no coverage, just one mistake or a court case can take everything away. A company could lose its license and may have to stop working.
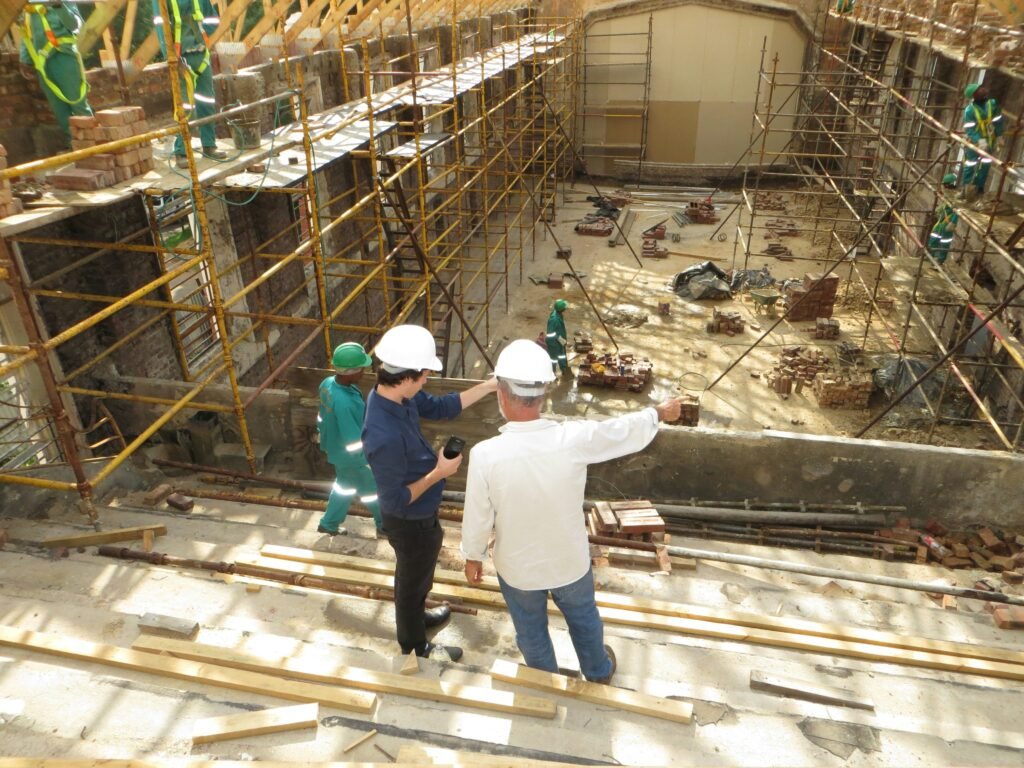
Building sites often change and are hard to manage. There are big machines, tough jobs, and lots of people moving around. Even small mistakes can lead to expensive fixes, high doctor bills, or long legal fights. If you go into a work area without the right safety plans, you put everything your company owns on the line, both people and money.
It does not matter if you are doing a home update or working on a big building job. It is important to have good coverage so you can stay safe at work. When you work with experts for contractor insurance in san antonio, you can feel sure your plan will follow state rules. The plan will also fit your work, the risks you have, and what your local project needs.
5 Critical Reasons Construction Companies Must Secure Liability Policies
1. Financial Protection Against Third-Party Property Damage
Accidents can happen, like if you hit a wall by mistake, or break water or power lines. A leak can also start when you do plumbing or electrical work. These things can hurt your property. General insurance steps in here. It can pay for fixing things or getting new ones. This keeps your money safe for your work.
2. Coverage for On-Site Bodily Injuries
If a client, someone who comes to the site, or even anyone passing by slips on something or gets hit by something that falls, the medical costs can rise quickly. This insurance will pay for those first hospital bills, rehab, and anything the court says you need to pay. It helps your company not use its own money for these things.
3. Fulfilling Legal and Licensing Requirements
State groups that handle rules, like TDLR or your city office, often need you to have active commercial general insurance before you get permits or work licenses. If you do not have proof of this coverage, you may be told to stop all work at once. You could also get big fines or lose your license for good.
4. Meeting Mandatory Contract and Client Demands
Project owners, real estate developers, and main contractors often need proof of insurance. This is shown with Certificates of Insurance (COI). You must show a COI before people will read your bid. If you do not have insurance, you will lose good chances to bid from the start.
5. Legal Defense Cost Safeguards
Lawsuits that are not important or get bigger than they should be are often seen in trade jobs. Your team may not be the cause. Still, you have to pay for lawyers, court fees, and help from other experts. These bills can grow fast. Your insurer will pay these costs for you right away.
Key Insurance Coverages to Include in Your Portfolio
| Coverage Type | Core Purpose | Typical Protection Focus |
| General Liability | Primary third-party protection | Property damage, bodily injury, personal injury |
| Workers’ Compensation | Employee injury coverage | Workplace accidents, lost wages, medical expenses |
| Commercial Auto | Work vehicle incidents | Accidents involving work trucks, vans, and haulers |
| Inland Marine | Tool & equipment safeguard | Stolen or damaged tools in transit or on-site |
Frequently Asked Questions (FAQ)
What is the standard policy limit for general liability coverage?
Most large building jobs need at least $1,000,000 for each case. They also need $2,000,000 to cover all cases together. If the job is more important, the company may need to have extra umbrella insurance.
Are independent subcontractors covered under a general contractor’s liability policy?
Subcontractors are not usually covered. Most of the time, they are told to get their own insurance. This helps protect them from any risks that may happen while they work.
How fast can a business get a Certificate of Insurance (COI)?
After you set up your policy with a provider you trust, you can usually get an official Certificate of Insurance online in a few hours.
Conclusion
Having good coverage for problems at work is not just another business cost. It is an important part of keeping your company going strong. There are many things that can happen. The right insurance can help your business handle these problems. It keeps your cash flow running when something goes wrong on the job. It also helps you follow the client’s rules, so you can go for new work and feel confident. If you work with local experts and get the right contractor insurance in san antonio, your business will be protected before your team starts on each new job site.